Tag: product management

  • Digital Payment Methods in India: UPI, Credit Cards and more

    Digital Payment Methods in India: UPI, Credit Cards and more

    We have come a long way from getting INR 10 cash from our mothers for Parle-G biscuit to making payment with single clicks on our phone.
    note: this image is generated with AI

    Cash was the only mode of payment in India — until we saw mass adoption of new technology and mobile phones.

    In India, we see new payment app released almost every month. While UPI payments had accelerated the digital payments space, there are several other modes of digital payments.

    Since 2016, I have worked in 5 Fintech companies across payment gateways, global money transfers and prepaid cards. In this blog, we’ll explore various payment modes available in India.

    • Bank account to Bank Account Transfer (e.g. NEFT)
    • Cards (Debit, Credit and Prepaid)
    • UPI
    • Digital Wallets
    • Pay Later

    Bank Account to Bank Account Transfer

    This mode of payment lets you send the money directly from your bank account to another bank account. NEFT, RTGS, IMPS fall under this category.

    In order to transfer money, you will need the full Bank Account details of the receiver like Account Number, Account Name, Bank Name, IFSC code and Branch Name.

    They work well when you have to transfer large amounts. This method is very popular when businesses have to pay for big invoices.

    However, it is highly inconvenient on online shopping sites or anything that demands instant payment confirmation to both sellers and buyers.

    Another drawback is that receiver may not always get the sender’s details. While some banks have tried to improve this, a lot of banks have not.

    Through IMPS you can send the money instantly, while NEFT and RTGS could take longer.

    NetBanking

    Netbanking emerged as an intermediate choice to make a payment. I’d like to think of it as a choice in between NEFT and Card. 

    This is how it works, if you are on a shopping site and you chose Netbanking, you are redirected to an authentication page. This is where you will either enter your password or OTP and then the payment is successful. You need not know seller’s bank account details. It is a step up from Bank to Bank transfer. It works only if you have a bank account and sufficient money in it.

    One of the limitations is that not all banks support this payment method.

    Cards

    There are 3 types of cards:

    • Debit
    • Credit
    • Prepaid — Debit cum Credit

    They come in a plastic or metal form. You can get a card either from your bank or any financial institute like American Express. Cards add a lot more convenience when compared to above 2 choices for payments.

    They come with controls like payment limits, blocking a card and changing PINs when required. While cards are issued by the banks, a card network provider like Rupay, Mastercard, Visa, Maestro is required. These Card Networks act as intermediate layer between Merchant’s bank, your bank and you. 

    Card Networks and banks work together towards fraud prevention and consumer protection. Because they offer these services, Card networks charge a certain fee on each transaction to the merchant. Depending on the fees sellers can choose which card to allow and which to avoid. You will notice American Express is not widely accepted at retail stores.

    All cards issued in India will work in India but for international payments, you might have to contact your bank. While many banks have made it easy in their apps, other banks still operate in traditional way.

    Debit Card

    Debit card is connected to your bank account. It works only if you have sufficient money in your bank account. And this is the key difference between your debit card and credit card. I will explain Credit Cards next.

    Many banks issue Debit cards free of cost when you open a bank account. It lets you pay at stores, online sites with ease. You can also control spends by setting up payment limits.

    Credit Card

    It’s in the name, it is a credit. Imagine getting a loan for 45 days without any interest. You get a certain limit, say INR 1,00,000. You can spend upto 1 Lac and pay the bill later. Of course, if you cannot pay that bill, you will be charged fees for the late payment. This is usually considered risky payment method because you may be tempted to pay more than you can afford.

    People are attracted to Credit cards because they offer some rewards. The more you spend, the more rewards you get. Rewards are usually in the form of points which can then be redeemed.

    Banks are quick to give out Credit cards with lower limits like INR 10,000 to INR 25,000 to masses. However, to get higher limits like INR 1,00,000+ requires certain income. Some banks also assess your spending capacity and your payment history. If you had missed credit card bill payments in the past, you are less likely to get higher limits.

    Paying credit card bills is also easy. You can directly pay from your bank application or use apps like Cred.

    Prepaid Cards — Debit cum Credit

    You will have to know some technicality to understand this payment method and why it is used. This type of card behaves like a Credit Card but does not have credit limit.

    A card has 16 digits card number. They are either printed on the card or shown in the mobile app. The first 6 digits of the card number is called BIN (Bank Identification Number). It helps identify the type of card. Numerous websites accept only Credit cards but not Debit cards. Debit cum Credit card solves this problem. They offer you a Card that acts as Credit Card but you will have to load money onto it. You can only spend what you have loaded. It is the BIN that identifies this card as Credit card.

    Niyo, Happay are couple of examples in India. Banks also directly offer Prepaid cards. Globally, apps like Wise, Revolut and Monzo are very popular. 

    I did a case study on Wise where I go in-depth about their UX 
    (Check it out here).

    In the screenshot, EUR 347.06 is the amount I can spend using my Wise prepaid card.
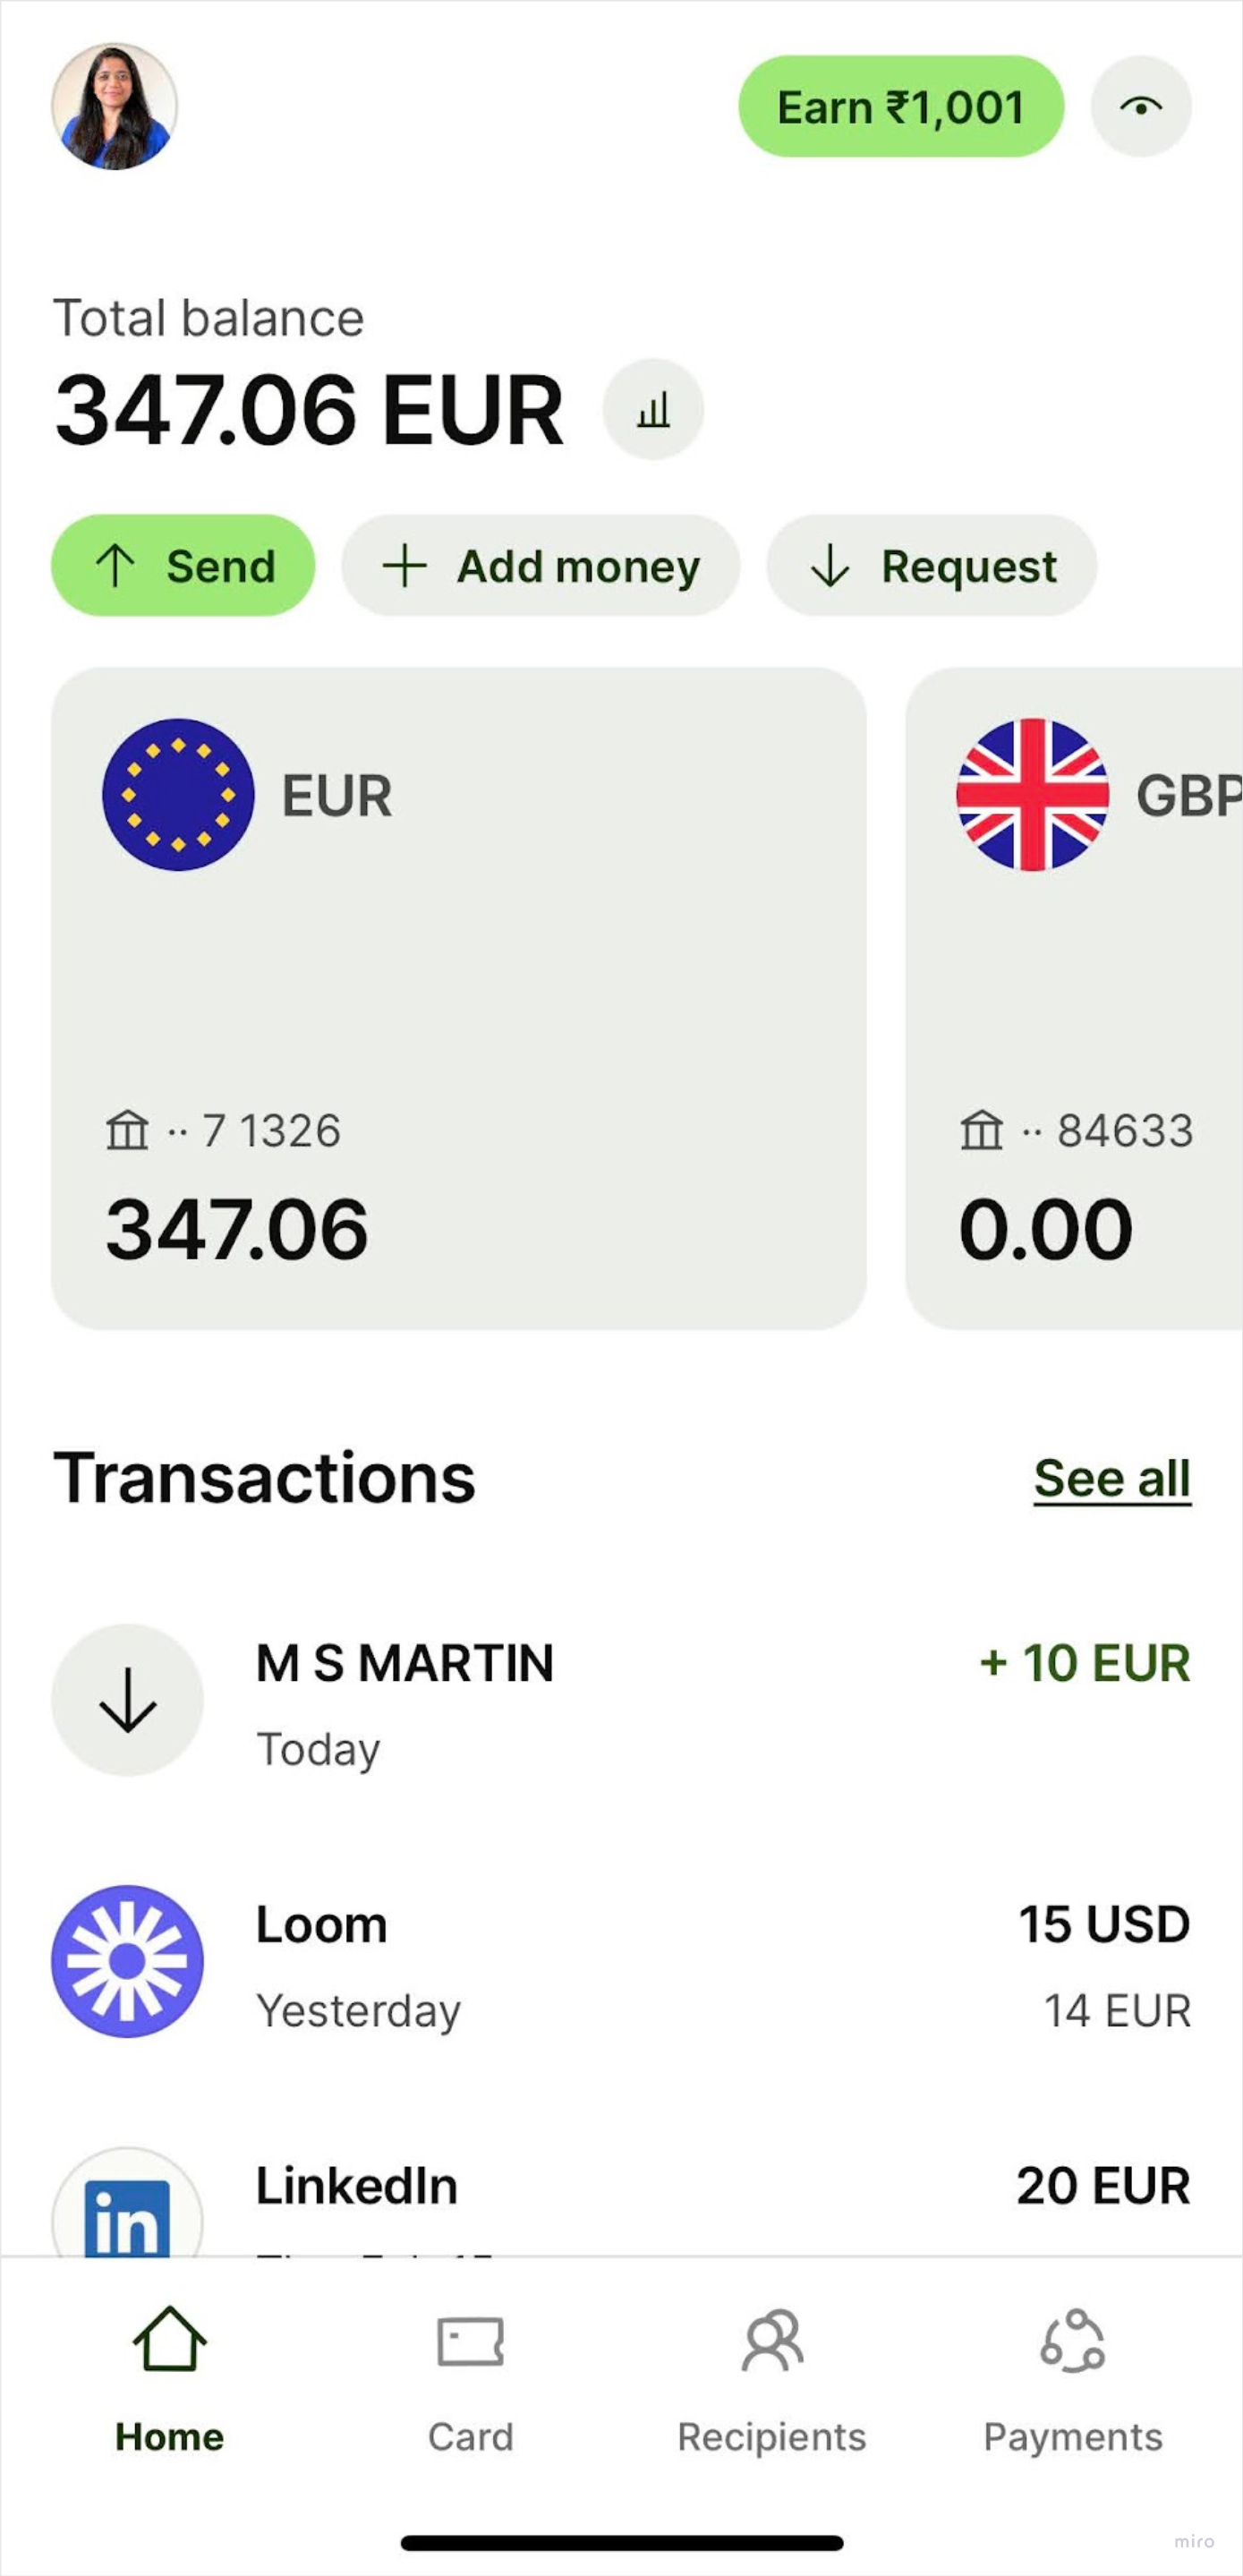
    This is a screenshot of Wise mobile app. It shows the account balance of 347 euros.

    Since they offer less risk to both banks and customers, while also solving a core need, prepaid cards became extremely popular in many countries.

    UPI

    Unified Payment Interface, or UPI has become a household name. Your grandparents might be already using it. It is used for peer to peer and peer to merchant payments.

    When it was first launched, you needed a UPI virtual address to send or receive payment. Nowadays, you only need phone number of the person. In the background, every user gets a virtual private address something like 99XXXXXXX@kotakbank to identify the unique user. UPI is always linked to your bank account which is also linked to the phone number.

    You do need a bank account to use UPI. Each bank might have different limits to send and receive money.

    As soon as banks adopted it, companies like Paytm, Phonepe, Bharatpe, Google Pay capitalised on the opportunity to make it easy for the merchants to receive payments via QR code.

    While UPI works beautifully for small payment amounts, NEFT and Cards are still the go-to choice for large sum of money.

    A simple google search should help you understand the scale of this technology and how it became a huge success. It’s an incredible story from digital India.

    There is another category of payments that you might have come across. These payment methods still use your bank account but they have different flavours.

    Digital Wallets

    Products like Paytm and Phonepe have popularised this type of payment method already. Almost every B2C product seems to offer “Wallet.”

    I will skip the technicality on how these Wallets are actually created and how they work in background.

    In order to use the Wallets, you first have to load the amount from your bank account. Usually, there is a limit between INR 10,000 to INR 20,000. Every month, you can load that amount and use it to make payment. To avail higher limits, you have to complete KYC within these apps.

    Products use Wallet as a hook to retain customers. For example, when you order food on Swiggy, they can give you some discount if you use their wallet. You will be tempted to load money in order to avail this discount.

    Wallets were very popular before UPI. You could transfer money from your wallet in Paytm to someone else’s Paytm wallet. It facilitated peer to peer transactions easily.

    Pay Later

    This is similar to how your shopkeeper in the neighbourhood used to give you “udhaar” or credit. When you shop online, you can choose to pay the amount later within X number of days. The number of days depend on multiple factors. Typically, you will see 30, 45 or 60 days. Lazypay is an example for Pay Later option. In Europe, Klarna Pay Later is quite popular. You will also be charged some interest amount.

    The biggest risk is the non-payment. Many people can buy once and never pay back. When companies offer this choice, they usually allocate a budget for such risky transactions.

    Another factor is, collection. Your neighbourhood shopkeeper can show up at your house but these companies cannot trace you easily. You will receive many calls but it’s easy to buy a sim card and discard it.


    If you found this interesting, you might be interested in a case study on UX of Indian & Dutch bank mobile app, check here.

    Also, don’t miss Swiggy (Indian) vs JustEatTakeaway(Dutch) case study. See here.
  • Micro-interactions in UX and why they exist

    Micro-interactions in UX and why they exist

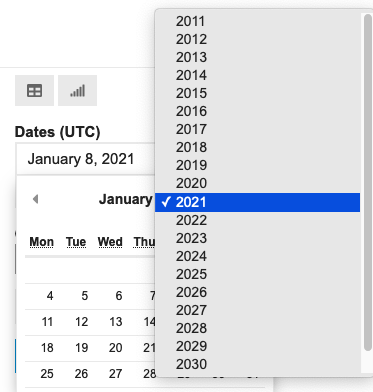
    Have you ever scrolled through an endless list of years just to find your birth year?

    Date picker. Image source: link

    It is a minor annoyance but annoyance, nonetheless. We encounter these micro-interactions in digital products every day.

    On a paper form, you simply write down your date of birth. Why can’t we do the same online?

    In the real world, “01st Dec, 1980,” “01/12/1980,” and “December 01, 1980” are all acceptable ways to write a date of birth. However, analyzing non-uniform data is challenging. Analysis becomes much simpler when dates follow a consistent format.

    This is why user input needs to be collected in specific formats — to maintain data consistency and uniformity. However, for the sake of solving this consistency problem, we cannot sacrifice user experience.

    In the above example, users should be able to both select and type the year. We can validate the entry immediately and prompt for corrections if needed. Put simply, there are always ways to enhance the experience.

    These seemingly tiny details are important in Product Design. This is why, Designers and Product Managers work together to design excellent products by performing research and user tests. Well, at least in theory.

    Let’s take a look at 4 interactions you must have encountered before.

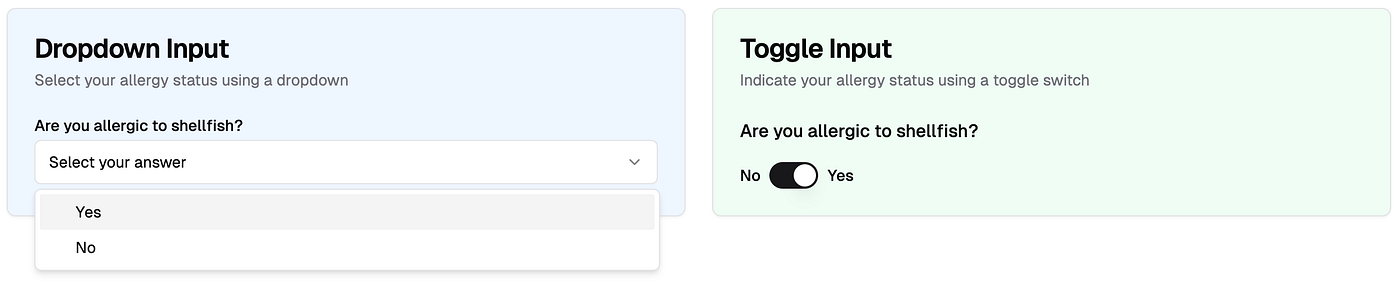
    When you have 2 choices in input → should it be dropdown or toggle?

    Would you have a preference? If it is single question, probably not. But imagine it is a medical form and they need to know all sorts of pre-existing conditions, say 20 questions. Would it be different then?

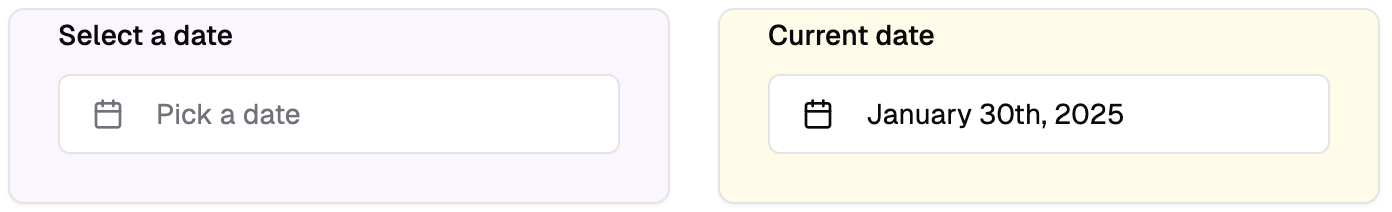
    Selecting date → what should be the default date on the date picker?

    Should it be blank? Should it default to current date or some arbitrary date? That’s a decision to be made.

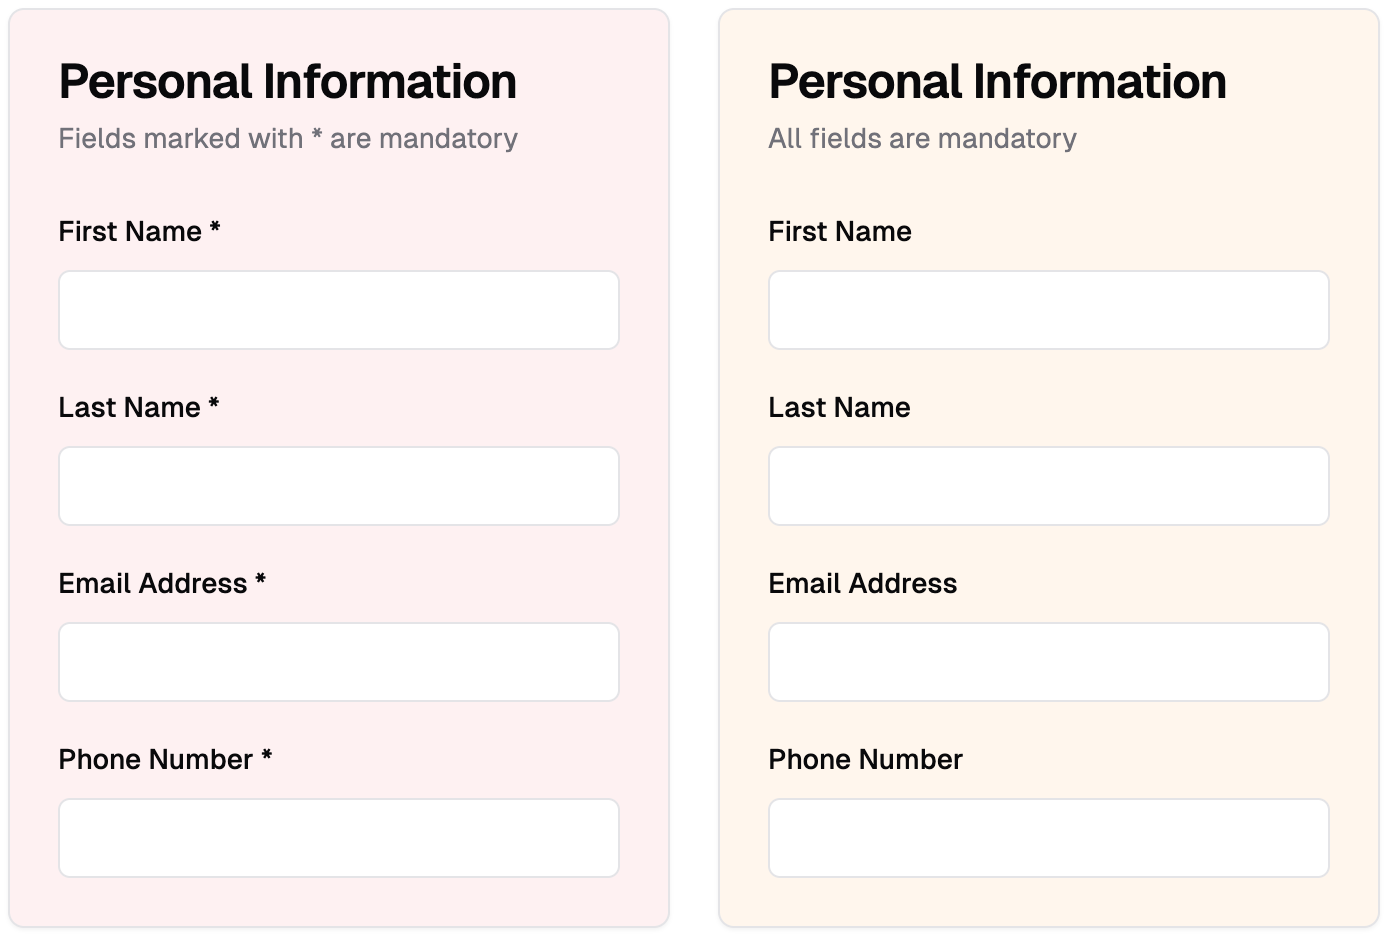
    Indicating mandatory inputs → should we indicate mandatory inputs for all via asterisk?

    Would you have a preference between 1st and 2nd? Imagine slightly longer form where 15 out of 20 questions are mandatory, what will be the design choice then?

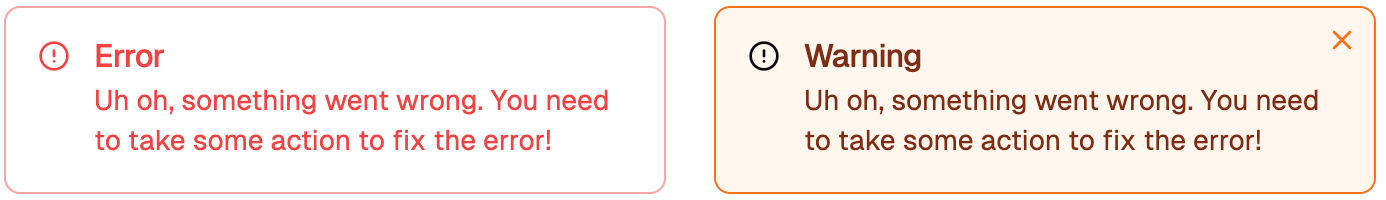
    Should the error message be dismissed automatically or by the user?

    It sounds like a no-brainer until you put it in a context and suddenly you don’t want to automatically dismiss the error.

    It is very tempting to choose one over the other. However, without proper product discovery, you might end up choosing the incorrect UI element. It is not the UI element, it is the placement of that element in the context of the product.

    Do this exercise — check a form, preferably a longer one, in your product or any other product. Try filling it without making any errors. Record that experience. Highlight minor annoyances.

    Why do some forms have bad user experience?

    That’s a really good question. The people who build these products often know the answer and it could be one of the following:

    1. Technically challenging: I say challenging not impossible because minor interactions are not impossible to change but they can take time or cause dependencies. You cannot simply change the Date Picker one fine day and not worry about impact on everything else. Think about data storage, analytics, operations work etc.
    2. Design team wants to adhere to some “core principles”: This may happen in certain companies where the design team has strong opinions on the UX. Sometimes, having strong design opinions can work in their favour but other times, it may not. Think of Airbnb; they seem to have strong design opinions but I often think their UX is more complicated than other booking sites.
    3. Time to build and Time to release: If you have ever worked in the Design, Product or Tech team, you will know that every discussion boils down to “We have a tight deadline therefore, only highest priority items can be fixed.” Inevitably, minor interactions are never highest priority. This is why, you will notice some popular products with poor UX.
    4. Design Debt: Just too many optimisations causes inaction. As a designer, if you list all the improvements for your product you are going to have at least 10–15 things on the highest priority. Knowing your team’s bandwidth, you may not even highlight those issues. Therefore, you continue to accrue debt.

    Is there no way out?

    Of course, there is. Every company eventually finds a way out to resolve these issues. However, the reasons to do so will depend on the company’s priorities for that month, quarter, or year.

    Let’s say, too many people drop off before completing a form and that causes users to not subscribe or pay. This is a huge risk. It affects business metrics. You bet, the whole team is going to work for next few weeks fixing tiniest of UX issues.

    Compare that to filling up a feedback form inside the dashboard, it is not perceived to be huge risk.

    It is a delicate dance between company priorities and great user experience.

    From my experience as a Product Manager, the best way to minimize this type of debt is to invest time upfront in discussing and debating on micro interactions, carefully weighing the pros and cons of each UI element before development begins.

    Which micro interactions have annoyed you recently?


    Shout out to my ex-designer colleagues — Anas, Nikos and Denis. They always challenged me to think differently. And I could nag them with my thought experiments.

    Note: All visuals in the example section have been generated using V0.dev product. I explored V0.dev a while back: check here

  • Detergent bottle cap design made me go “Aha”

    Detergent bottle cap design made me go “Aha”

    Imagine this.

    It’s laundry day.

    Argh. You already hate it.

    You load the machine with clothes.

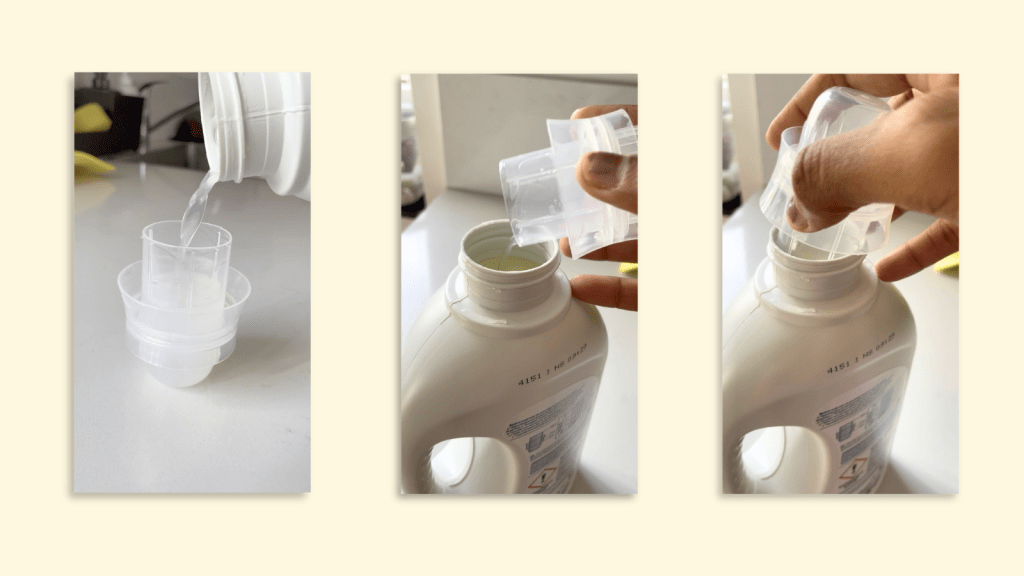
    You unscrew the cap of the detergent bottle.

    Pour the liquid.

    Put the cap back on and Ahhh! Some detergent leaks out.

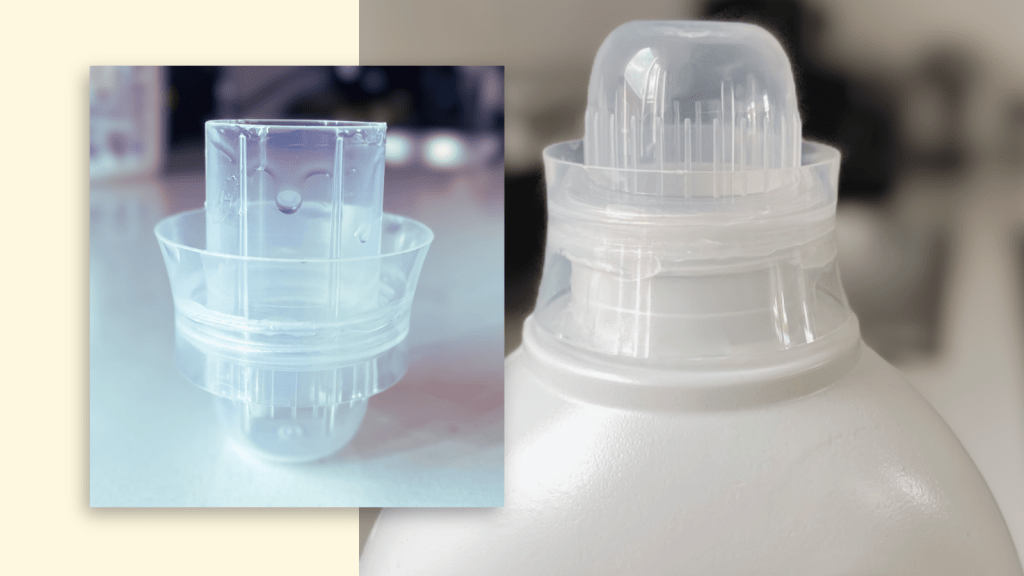
    Now, take this Detergent Bottle Cap. Do you notice anything different?

    It’s brilliant design.

    It looks like a no-brainer and yet, you don’t see it everywhere.

    It is not a ground breaking invention. Perhaps, no one even notices it. It makes an impact on your daily routine for just a fraction of second. To me, such designs are very impactful and thoughtful.

    Designing a user-friendly bottle cap doesn’t directly increase revenue. Consumers don’t choose a brand solely for its superior cap design. Yet, companies invest time and effort to enhance these small details, making your life a little easier.

    Until I read the book, “Design of Everyday things” by Don Norman, I never paid attention to the design of physical products. And until I became a product manager, I never really paid attention to the design of digital products either. But now, I think about product’s design all the time.

    You might think, “How hard can this be? It’s just a bottle cap.

    “While that’s mostly true, manufacturing physical goods is quite challenging. It involves long, tedious processes. You can’t simply change the design in your cool software and expect to release it in the next batch. Digital products, on the other hand, have that advantage of “rolling back” a release when it doesn’t meet expectations. With physical goods, you can’t simply roll back—there are dependencies from design to production phase.

    Most manufacturing companies often outsource the production of certain parts. You design a part, create specifications for it, send it to your manufacturing unit. Now, this unit needs to support the design. If the manufacturer does not have the right equipment, they have to procure it. It is not same as spinning up another server with a single line of code or one-click action to scale up your digital product. Of course, I am over simplifying here but you get the idea.

    When you take into account all these factors, you suddenly realize it may not have been an easy task to push such a design into production, especially when most detergent bottles in the market come with a standard cap.

    Of course, once it becomes a standard design, it makes waves, and production becomes much easier.

    So if you cannot change design on the fly, how do you iterate? How does the team validate the design choice?

    Interestingly, digital and physical products share similarities in this aspect. You don’t always need to go straight to production. Instead, you can test your concept by creating a prototype—a working model that illustrates the user’s experience. This prototype serves as a tool to validate both your design and concept.

    There is a cool video on Youtube on how car companies use clay modeling to experiment with design concepts.

    Digital products also have prototypes. Check this prototype from Figma Community member. You can interact with a mobile app design without involving the software developers.

    But, I digress.

    For now, my detergent bottle has impressed me. It solves a tiny problem in my life and I derive immense satisfaction from it. Their core product is already good but design like this makes me go “Aha😊.” That’s the moment you want to have from your customers.